Starting a business in the United States is more straightforward than most people expect. There is no single federal business license, most registrations happen online, and many first-time founders are up and running within a few weeks. What trips people up is doing the steps in the wrong order, or skipping one that comes back to bite them at tax time.
This guide walks through the process in a practical sequence, from testing your idea to landing your first customers. Rules vary by state and city, so treat this as a roadmap and confirm the specifics with your state and local offices.
Step 1: Validate Your Business Idea
Before you spend money on registrations or equipment, confirm that people will actually pay for what you plan to sell. Talk to at least ten potential customers. Look up competitors on Google Maps and read their reviews to see what customers love and what they complain about. If possible, presell a few orders or book a few paid jobs. Real money from real customers is the strongest proof you can get.
Still choosing an idea? Start with our list of the best small business ideas to start in America.
Step 2: Write a Simple Business Plan
A business plan does not need to be 40 pages. At minimum, write down who your customers are, what you will charge, what it costs to deliver, how you will find customers, and how much money you need to get started. Lenders and investors will ask for a fuller version, and even if you self-fund, the exercise forces you to check your math. Our guide on how to write a business plan step by step breaks down every section.
Step 3: Choose a Business Structure
Your structure affects your taxes, your paperwork, and how much of your personal property is exposed if something goes wrong. The most common options are:
- Sole proprietorship: the default if you start doing business alone without registering an entity. It is simple and cheap, but there is no legal separation between you and the business.
- General partnership: the default for two or more owners. Like a sole proprietorship, owners are personally liable for business debts.
- Limited liability company (LLC): a popular choice for small businesses because it separates business liabilities from your personal assets while keeping taxes relatively simple. See our full guide on how to start an LLC in the USA.
- Corporation: a C corporation or an S corporation election makes sense for some businesses, especially those raising outside investment or with higher profits. It comes with more formalities.
If you are unsure, a short consultation with a CPA or business attorney is money well spent.
Step 4: Pick and Protect Your Business Name
Search your state business database to make sure your name is available, run a quick search in the USPTO trademark database, and check whether a matching domain and social media handles are free. If you will operate under a name different from your legal entity name, you will usually need to file a DBA (doing business as), also called an assumed or fictitious name.
Step 5: Register With Your State
LLCs and corporations are created by filing formation documents with your state, usually through the Secretary of State website. State filing fees for an LLC range from about $35 to $500 depending on the state, and some states also charge annual report fees or franchise taxes. Sole proprietors generally do not file formation paperwork, though they may still need a DBA and local licenses.
Step 6: Get an EIN From the IRS
An Employer Identification Number (EIN) works like a Social Security number for your business. You need one if you hire employees or form a multi-member LLC or corporation, and most banks ask for one to open a business account. You can apply online through the IRS website for free. Avoid third-party sites that charge a fee for this.
Step 7: Get the Right Licenses and Permits
Licensing happens at several levels, and requirements depend on your industry and location:
- Federal: only needed for regulated activities such as alcohol, firearms, aviation, or commercial trucking.
- State: professional and occupational licenses (contractors, cosmetologists, child care providers, and many more) and a sales tax permit if you sell taxable goods or services.
- Local: a general business license, zoning approval, home occupation permits, signage permits, and health permits for food businesses.
Call your city or county clerk and ask what applies to your business. The SBA business guide is also a useful starting point.
Step 8: Open a Business Bank Account
Keep business and personal money separate from day one. It makes bookkeeping and taxes far easier, and for an LLC or corporation it helps protect your liability shield. Bring your formation documents, EIN, and ID to the bank.
Step 9: Fund Your Business
Most small businesses start with the owner’s savings, but there are other options:
- Friends and family: put any agreement in writing, even if it feels awkward.
- SBA microloans: loans of up to $50,000 made through nonprofit intermediary lenders, often paired with business coaching.
- SBA 7(a) loans: government-backed loans issued by banks and credit unions for working capital, equipment, and real estate.
- Business credit cards and equipment financing: useful for smaller purchases, but watch interest rates closely.
- Crowdfunding and grants: grants exist but are competitive, so do not build your plan around winning one.
Step 10: Understand Your Taxes
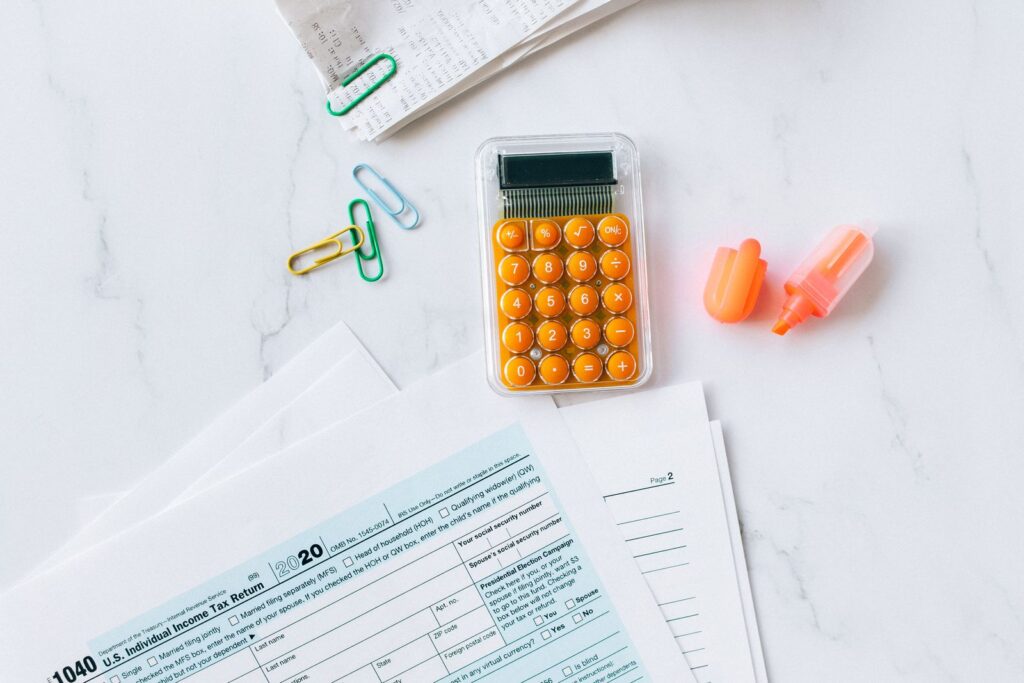
Taxes are where new owners most often get surprised. The basics:
- Income tax: sole proprietorships, partnerships, and most LLCs are pass-through entities, so profits are reported on the owners’ personal returns.
- Self-employment tax: if you work for yourself, you pay both halves of Social Security and Medicare, a combined 15.3% on most net earnings.
- Estimated taxes: since no employer withholds for you, you will generally make quarterly estimated payments to the IRS and your state.
- Sales tax: most states require you to collect and remit sales tax on taxable sales.
- Payroll taxes: once you hire employees, you must withhold and pay payroll taxes and file the related forms.
A good bookkeeper or CPA usually pays for themselves in saved time and avoided penalties.
Step 11: Get Business Insurance
Common policies include general liability, professional liability (errors and omissions), commercial auto, and commercial property coverage. Many small businesses bundle these into a business owner’s policy (BOP). Once you hire employees, workers’ compensation insurance is required in nearly every state.
Step 12: Set Up Simple Systems
Choose accounting software, a way to send invoices and take payments, and a system for tracking customers and appointments. Keep every receipt. A few minutes of bookkeeping each week beats a panic in April.
Step 13: Launch and Market Your Business
Start with the channels that cost little and convert well:
- Claim and complete your Google Business Profile, including photos, hours, and service areas.
- List your business in reputable local directories so customers can find you in more places.
- Build a simple website with clear services, prices or price ranges, and contact details.
- Ask every happy customer for a review and a referral.
- Join your local chamber of commerce and community groups.
Common Mistakes to Avoid
- Spending heavily on branding, equipment, or office space before you have paying customers.
- Mixing personal and business money.
- Ignoring quarterly estimated taxes.
- Underpricing to win work, then burning out on jobs that barely make money.
- Skipping insurance to save a few hundred dollars a year.
Final Thoughts
You do not need everything figured out to start. Validate the idea, get the legal basics right, and focus on serving your first customers well. Most of the rest gets easier once money is coming in and you are learning from real feedback.